



 Yaro Insider
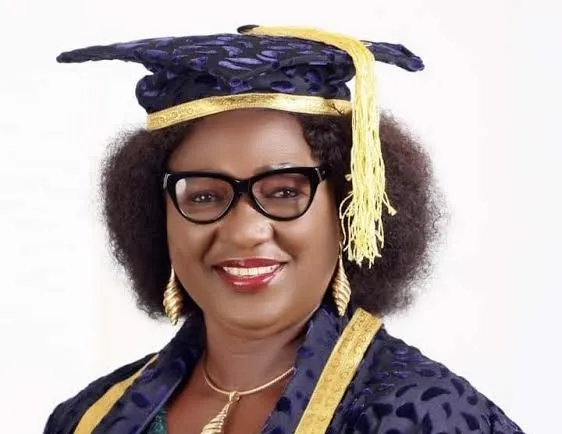
The University of Calabar is facing questions over financial management following a review that identified about ₦408.78 million in financial irregularities during the period when Professor Florence Obi was Vice-Chancellor.
According to the financial review reported on September 30, 2026, the findings cover nine separate issues involving internally generated revenue, cash advances, payments, travel expenses and financial documentation.
The largest finding involves ₦264.36 million in internally generated revenue that the review said was collected but not remitted as required.
Another ₦47.7 million in cash advances was reportedly not properly accounted for.
The review also identified ₦54.35 million in cash advances allegedly granted above the approved limit. Combined, the two cash-advance findings amount to more than ₦102 million.
Other issues reportedly identified include a ₦33.68 million payment described as doubtful out-of-pocket expenses and ₦8.68 million in irregular travel payments.
The review also raised questions about payments made without pre-payment checks, payments without adequate supporting documents, compliance with the Federal Government’s e-payment policy and international travel expenses allegedly made without the required approval.
Florence Obi served as Vice-Chancellor of the University of Calabar from December 2020 until December 2025. She was therefore the institution’s chief executive during the 2024 period covered by the review.
However, financial findings should not automatically be treated as proof that an individual personally stole or misappropriated funds.
The key issue is whether the identified amounts were subsequently reconciled, recovered, properly documented or otherwise explained by the institution and the officials responsible for the transactions.
The University of Calabar itself publishes financial statements, while the Federal Government’s Open Treasury platform also provides budget-performance information for the institution. These records provide avenues for further examination of how public funds were received and spent.
The reported findings therefore raise questions that deserve clear answers.
Was the ₦264.36 million eventually remitted?
What happened to the ₦47.7 million in cash advances that the review said could not be properly accounted for?
Were the disputed payments subsequently regularised or recovered?
Were any officials asked to explain the findings?
And were recommendations arising from the financial review implemented?
Those questions matter because the University of Calabar is a federal institution funded through public resources.
Financial accountability does not end when money is approved or spent. The records must show where the money went, what it was used for and whether the transactions complied with applicable rules.
The reported findings provide a basis for asking those questions. They do not, by themselves, establish criminal liability against Professor Florence Obi or any other individual.
What remains important is what the official records, responses and any subsequent investigations ultimately show.