



 Yaro Insider
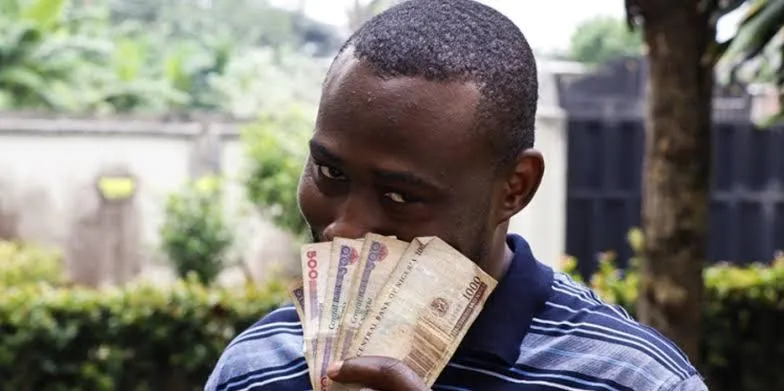
Payday no longer feels like the beginning of a comfortable month. It feels like a countdown.
Salary enters the account, and within days, a large part of it is already gone.
Food, transport, rent, electricity, school fees, data, medical expenses and family responsibilities are competing for the same income. By the time the basic bills are settled, little may remain for savings or emergencies.
Nigeria’s ₦70,000 national minimum wage, introduced in 2024, has also come under renewed pressure. Labour leaders said in August that rising living costs had eroded its value and called for another review.
The problem is not simply that salaries are low.
It is that the cost of maintaining an ordinary life has risen faster than many incomes.
A worker earning ₦200,000 may look comfortable on paper. But after transport, feeding, rent contributions, electricity, phone bills and support for relatives, the balance can quickly become insignificant.
For workers earning less, the pressure is even greater.
A recent BudgIT report cited by The Guardian found that an adult in Ekiti could require about ₦62,739 a month just to meet the minimum cost of a healthy diet. That would leave only about ₦7,261 from a ₦70,000 minimum wage for every other expense.
This explains why salary increases do not always translate into a better standard of living.
If someone moves from ₦150,000 to ₦200,000 a month but the cost of food, transport and housing rises significantly, the extra ₦50,000 may disappear without creating any meaningful financial improvement.
For many households, saving has therefore become a luxury rather than a normal financial habit.
An unexpected hospital bill, vehicle repair, job loss or family emergency can force people to borrow money or depend on relatives.
There is also a wider problem.
Workers are increasingly being judged by their salaries while the economy is being priced according to expenses they cannot control. A person’s income may remain unchanged while rent is renewed at a higher rate, food prices increase and transportation becomes more expensive.
The result is a growing gap between earning money and actually having money.
That may be the new Nigerian financial reality.
Salary comes.
Bills arrive.
The money disappears.
And the next payday begins another cycle.

 Precious Olamide
 Nanah Usman